Why Analysts Disagree on Hanwha Ocean's Price Target
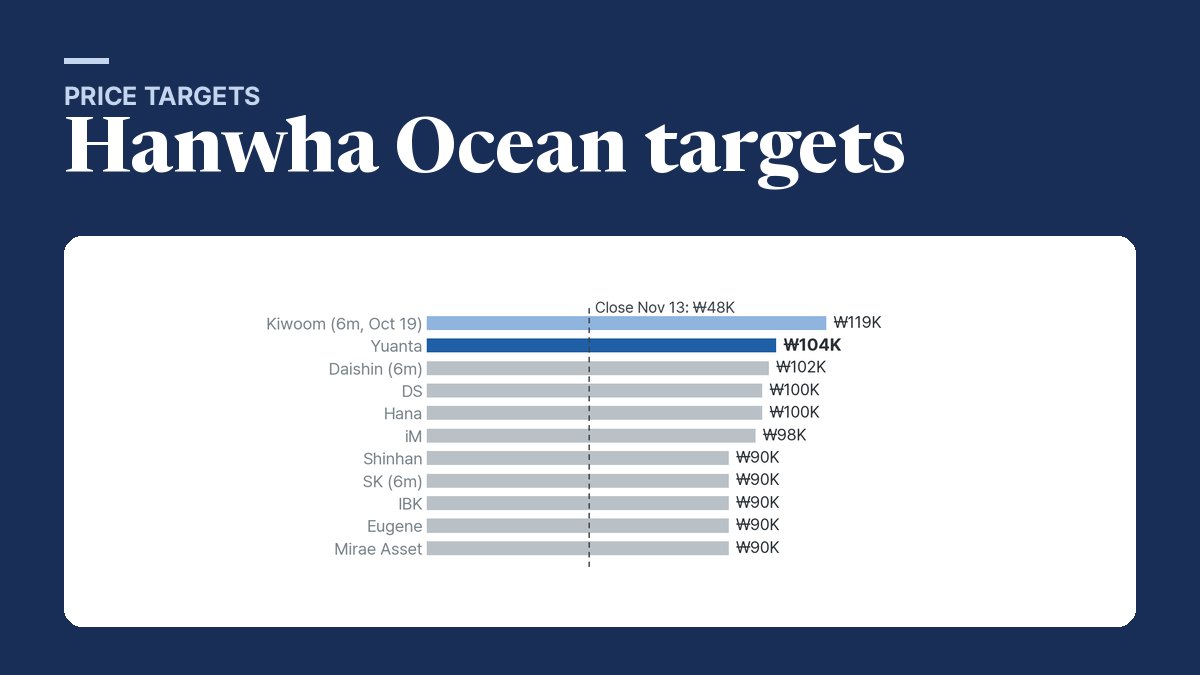
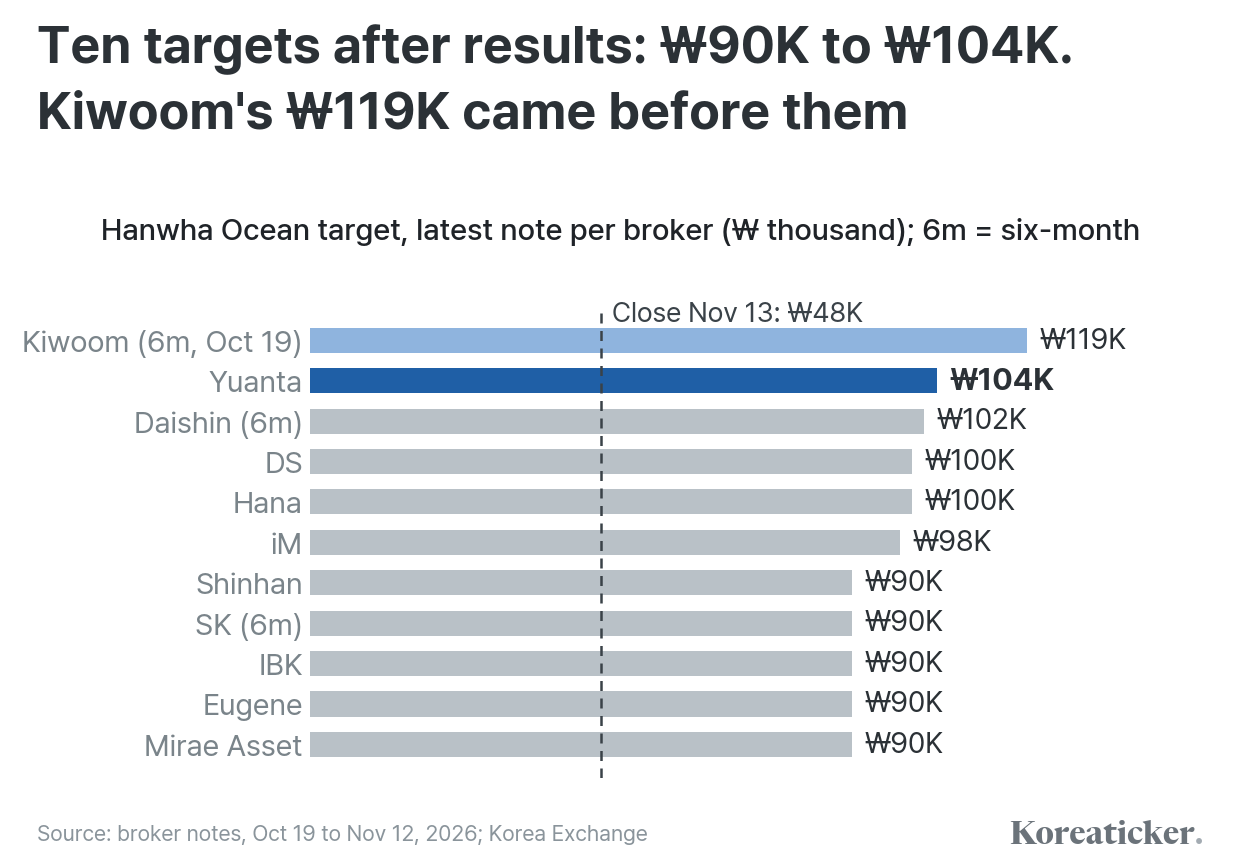
Hanwha Ocean closed at ₩48,350 on November 13, about $36. After its third-quarter results on October 28, ten Korean brokers published new targets between ₩90,000 and ₩104,000. The horizons differ: two of the ten are six-month targets, six are 12-month and two notes do not say.
That looks like agreement. The notes underneath use three different yardsticks and earnings from different years. If they agree on the answer, where do they actually disagree, and does it matter to someone holding the stock?
The short answer
- Every broker that updated after the results cut its target, most by 25% to 43%. Five landed on exactly ₩90,000
- They got there with price-to-earnings on 2027, 2028 or a blend of both years, price-to-book on 2027 or 2028 book value, and in one case a value per won of order backlog
- The widest single gap is over US naval work. Shinhan and DS took out the premium they had paid for it, and iM cut its multiple over it. Daishin kept a 10% premium, and Yuanta values it separately at ₩11.7 trillion, 37% of its target
- On commercial ships, two brokers cut their multiples on worries that China's new shipyard capacity will end the upcycle
What each broker assumed
Hanwha Ocean (042660.KS), called Daewoo Shipbuilding & Marine Engineering until 2023, builds LNG carriers and container ships, along with offshore platforms and naval ships including submarines. Hanwha Aerospace owns 30.4% of it. The Hanwha Ocean stock page has the dollar price and the closest US peer.
| Ticker | What it does | Close, Nov 13, 2026 | Market cap | P/E, trailing | P/B |
|---|---|---|---|---|---|
| 042660 (Korea Exchange) | Commercial and naval ships, offshore platforms | ₩48,350 | ₩14.8T (about $11.0B) | 7.6 | 1.99 |
P/E on net profit to shareholders for October 2025 to September 2026; P/B on equity at September 30, 2026.
| Broker, date | Target (₩) | Target horizon | Earnings or book value used | Multiple and where it came from | US naval work |
|---|---|---|---|---|---|
| Kiwoom, Oct 19 (before results) | 119,000 (cut) | 6 months | 2028 EPS ₩7,534 | 15x, cut from 23x: the average of past shipbuilding booms | Not stated |
| Yuanta, Nov 12 | 104,000 (from 179,000) | 12 months | 2027 order backlog ₩27.0T; naval after-tax operating profit | Backlog x 0.7; US naval profit x 20; other naval profit x 15 | Valued separately, ₩11.7T |
| Daishin, Nov 3 | 102,000 (from 139,000; the cover line says 93,000) | 6 months | 2028 EPS ₩7,247 | 14.1x: global shipyard peers at 12.8x plus 10% | Reason for the 10% premium |
| DS, Oct 28 | 100,000 (from 145,000) | Not stated | 12-month forward EPS ₩6,062 | 16.5x: its own 2025 average P/E less 20% | Export naval premium removed |
| Hana, Oct 28 | 100,000 (from 175,000) | 12 months | 2028 book value per share ₩39,986 | 2.5x book | Not stated |
| iM, Oct 28 | 98,000 (from 134,000) | 12 months | 2027 book value per share ₩28,108 | 3.5x book, cut | Lower US expectations given as the reason for the cut |
| Shinhan, Oct 28 | 90,000 (from 130,000) | Not stated | Average of 2027 and 2028 EPS, ₩5,677 | 16.1x: 2007 shipbuilder average of 16.9x less 5% (was plus 10%) | Premium dropped |
| SK, Oct 28 | 90,000 (from 110,000) | 6 months | 2028 EPS ₩6,663 | 13x, cut | Not stated |
| IBK, Oct 28 | 90,000 (from 120,000) | 12 months | 2027 to 2028 forecasts, cut on a ₩1,400 dollar | 19.8x: 2025 big-three shipbuilder average less 40% | Not stated |
| Eugene, Oct 28 | 90,000 (from 137,000) | 12 months | 2028 book value per share ₩35,174 | 2.7x book, from a 17.8% long-run return on equity | Not stated |
| Mirae Asset, Oct 28 | 90,000 (from 128,000) | 12 months | 2028 EPS ₩6,600, cut from ₩7,506 | 14x, cut from 17x | Recovery 'depends on' US business |
Every note rates the stock a buy. Targets in dollars at ₩1,350: $67 to $77 after the results, $88 for Kiwoom's pre-results note.
Same price, different maths
Choosing a year matters as much as choosing a multiple. Mirae Asset's 2028 EPS forecast of ₩6,600 is 16% above the ₩5,677 Shinhan uses, an average of its 2027 and 2028 forecasts. So Shinhan pays more per won of profit, 16.1 times against 14, and still lands at the same ₩90,000.
The book-value brokers reach the same zone from the balance sheet. iM pays 3.5 times 2027 book value, Hana 2.5 times 2028 book value; both end up near ₩100,000.
Eugene derived its 2.7 times from a long-run return on equity of 17.8% against a 7.1% cost of equity. For a holder that ratio is a useful check: the target holds only if Hanwha Ocean keeps earning returns well above what shareholders could get elsewhere.
Where the notes split on US naval work
Four notes say they now pay less for a US Navy business than before. Shinhan swapped a 10% premium for a 5% discount after Hanwha lost the Canadian and Polish submarine contests and posted a third-quarter loss on naval ships.
DS took 20% off its own 2025 average multiple to strip out the naval export premium, citing delays in US and overseas naval orders. iM cut its book multiple for the same reason. Mirae Asset wrote that any recovery in the valuation depends on the US business becoming real.
Daishin moved the other way within a lower target. Its 10% premium over global shipyards rests on US naval orders.
Daishin's note, published November 3, reported that Hanwha Defense USA had won a $269 million order for one US Navy medium landing ship, to be built at Hanwha Philly Shipyard, with options for three more and construction due to start in the fourth quarter of 2027.
Yuanta is the clearest case. It values the commercial business at ₩18.9 trillion, 0.7 times a ₩27 trillion backlog, and the US naval business at ₩11.7 trillion, 20 times ₩584 billion of after-tax operating profit from ships built in Korea and in the US.
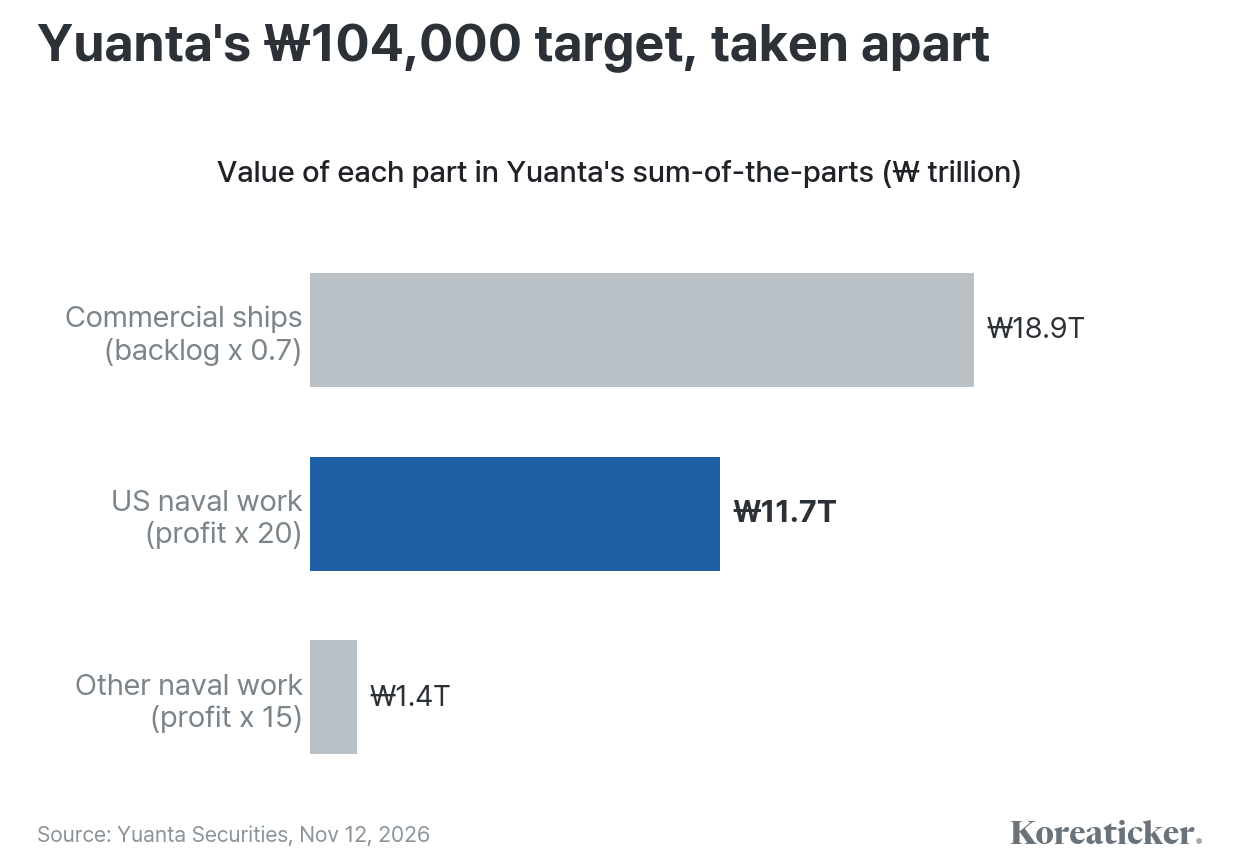
Take the US naval line out and Yuanta's own figures give about ₩66,000 a share, by our arithmetic, below every other target.
That one line is the widest gap between the notes: Yuanta counts US naval work at ₩11.7 trillion, while Shinhan's ₩90,000 gives it no premium at all.
Commercial ships: a peak in sight?
The commercial side is the largest part of Yuanta's value, and here the brokers worry about the cycle. SK and Kiwoom both cut their multiples over aggressive capacity expansion at Chinese shipyards and the risk that the commercial upcycle peaks.
Mirae Asset gave the mechanics. The commercial margin was 17.4% in the third quarter; it expects margins to stay around 18% through 2028 rather than keep rising. The boost from higher-priced orders taken since 2024 is close to its peak, and LNG carriers fall from 53.6% of the mix in the third quarter to 35% in 2027.
The dollar is the other lever. IBK lowered its long-run exchange rate assumption from about ₩1,450 to ₩1,400 per dollar and cut its 2027 and 2028 forecasts with it, since ships are priced in dollars and booked in won.
A US holder gets the opposite effect on the share price: a stronger won lowers reported profit but raises the dollar value of each won-priced share.
What to watch next
Eugene expected a Thai frigate contract, where Hanwha Ocean has been chosen, to be signed by the end of 2026, and noted a bid for an offshore production vessel for Namibia's Venus field that, if won, would add revenue from 2027 to 2030.
Neither is US naval work, but both test whether the naval and offshore lines can lift the forecasts that several brokers cut.
The US side moves on contracts. A second US Navy hull or progress on the Korea-US shipbuilding cooperation, which Korean brokers call MASGA, would bear on whether brokers value US naval work separately, one of several differences between the notes. They also differ on which year of earnings they use and on what multiple or yardstick they apply to it.
For US investors
How US investors can own Hanwha Ocean
Sources and notes
- Kiwoom Securities, 새로운 성장 동력이 필요 (Oct 19, 2026), p1. stock.pstatic.net
- Yuanta Securities, (FY25) 높은 산, (FY26) 깊은 골, 적막한 산하 (Nov 12, 2026), p1 to p2. stock.pstatic.net
- Daishin Securities, 특수선 모멘텀 시그널 (Nov 3, 2026), p1. stock.pstatic.net
- DS Investment & Securities, 점차 회복할 실적. 해양과 특수선 수주가 관건 (Oct 28, 2026). stock.pstatic.net
- Hana Securities, 일회성 비용과 환율 영향으로 기대치 하회 (Oct 28, 2026), p1. stock.pstatic.net
- iM Securities, 3Q26: 기대가 걷힌 자리 (Oct 28, 2026). stock.pstatic.net
- Shinhan Investment, 상선은 견조, 할증은 내려놓을 때 (Oct 28, 2026), p1. stock.pstatic.net
- SK Securities, 상선만으로는 부족하다 (Oct 28, 2026), p1. stock.pstatic.net
- IBK Investment & Securities, 3Q26 Review: 첫 고비는 넘겼다 (Oct 28, 2026), p1. stock.pstatic.net
- Eugene Investment & Securities, 상선 방어 성공, 해양과 특수선 반전 필요 (Oct 28, 2026). stock.pstatic.net
- Mirae Asset Securities, 돌파구가 필요한 시점 (Oct 28, 2026), p1. stock.pstatic.net
- Korea Exchange closing price for 042660, Nov 13, 2026, as listed on Naver Finance daily prices: finance.naver.com Trailing net profit and equity from the company's quarterly and half-year reports on DART: dart.fss.or.kr (search 042660)
Reports were found through Naver Finance's research list and cover every broker with a Hanwha Ocean target published from Aug 16 to Nov 16, 2026, using each broker's latest note. Daishin's cover line reads ₩93,000, but its text and its calculation both give ₩102,000, which we use. The ₩66,000 figure removes Yuanta's US naval line and divides the rest by its 306 million shares. Won converted at ₩1,350 per dollar, the site's fixed reference rate rather than a dated market rate.
For information only, not investment advice. See our full disclaimer.